Structured eInvoices are becoming mandatory across Europe and the UK. Ireland’s programme starts first. Here is what businesses need to know.
Across Europe and the UK, invoices are moving from PDFs to structured eInvoices(EN 16931, typically on Peppol). The EU’s VAT in the Digital Age (ViDA) rules make that mandatory for cross-border invoices between EU countries from 1 July 2030, and several member states already require it domestically. The UK will require VAT-registered businesses to issue and receive eInvoices from 1 April 2029. Whether that data is later reported to HMRC is still under consultation.
Ireland is on the same path, and it is moving sooner. Public bodies have had to receive structured eInvoices (B2G) since 2019. What is now coming is B2B: invoices between businesses, plus real-time reporting to Revenue. Revenue’s 21 October 2026 update sets out that programme. VAT rates and the VAT return stay the same. What changes is how invoices are issued, received, and reported.
Two things are happening at once in Ireland:
1. Exchange. Structured eInvoices travel between supplier and customer on Peppol.
2. Real-time reporting. For in-scope suppliers, a subset of that invoice data is also sent to Revenue when the invoice is issued.
Celtrino is already a certified Peppol Access Point, so you can send and receive structured eInvoices today, in Ireland and on Peppol more widely. Use our web portal, or we integrate with your ERP. Whichever is easiest. The extra reporting leg to Revenue (the fifth corner) needs Revenue’s technical specifications before anyone can build it. Those specs are not published yet.
Key dates
| Date | What it means |
|---|---|
| 1 January 2027 | Revenue becomes Ireland’s Peppol Authority. This is also the date used to identify large corporates for Phase One. No eInvoicing or reporting obligation starts on this date. |
| 2027 | Revenue will issue a business identifier where a VAT number is not already in place. |
| 1 January 2028 | Second snapshot date for Large Corporates Division businesses that join Phase Two. |
| 1 November 2028 | Phase One. VAT-registered large corporates (about 2,400 businesses, identified by Revenue’s Large Corporates Division on 1 January 2027) must issue structured eInvoices for domestic B2B supplies and report a subset of that data to Revenue in real time. Every business in Ireland must be able to receive eInvoices, including public bodies. |
| 1 November 2029 | Phase Two. Issue-and-report expands to Irish-established VAT-registered businesses engaged in cross-border trade in the EU, plus remaining Large Corporates Division businesses identified on 1 January 2028. |
| 1 July 2030 | Phase Three. EU ViDA rules become mandatory for cross-border invoices between EU countries. The monthly VIES statement is removed. Businesses still file a VAT return. |
If you are not a Phase One issuer, you may still need to receive structured eInvoices from 1 November 2028. A large corporate supplier can send you one without asking first. A PDF or a scan sent by email is not an eInvoice.
What is changing: Peppol and the five-corner model
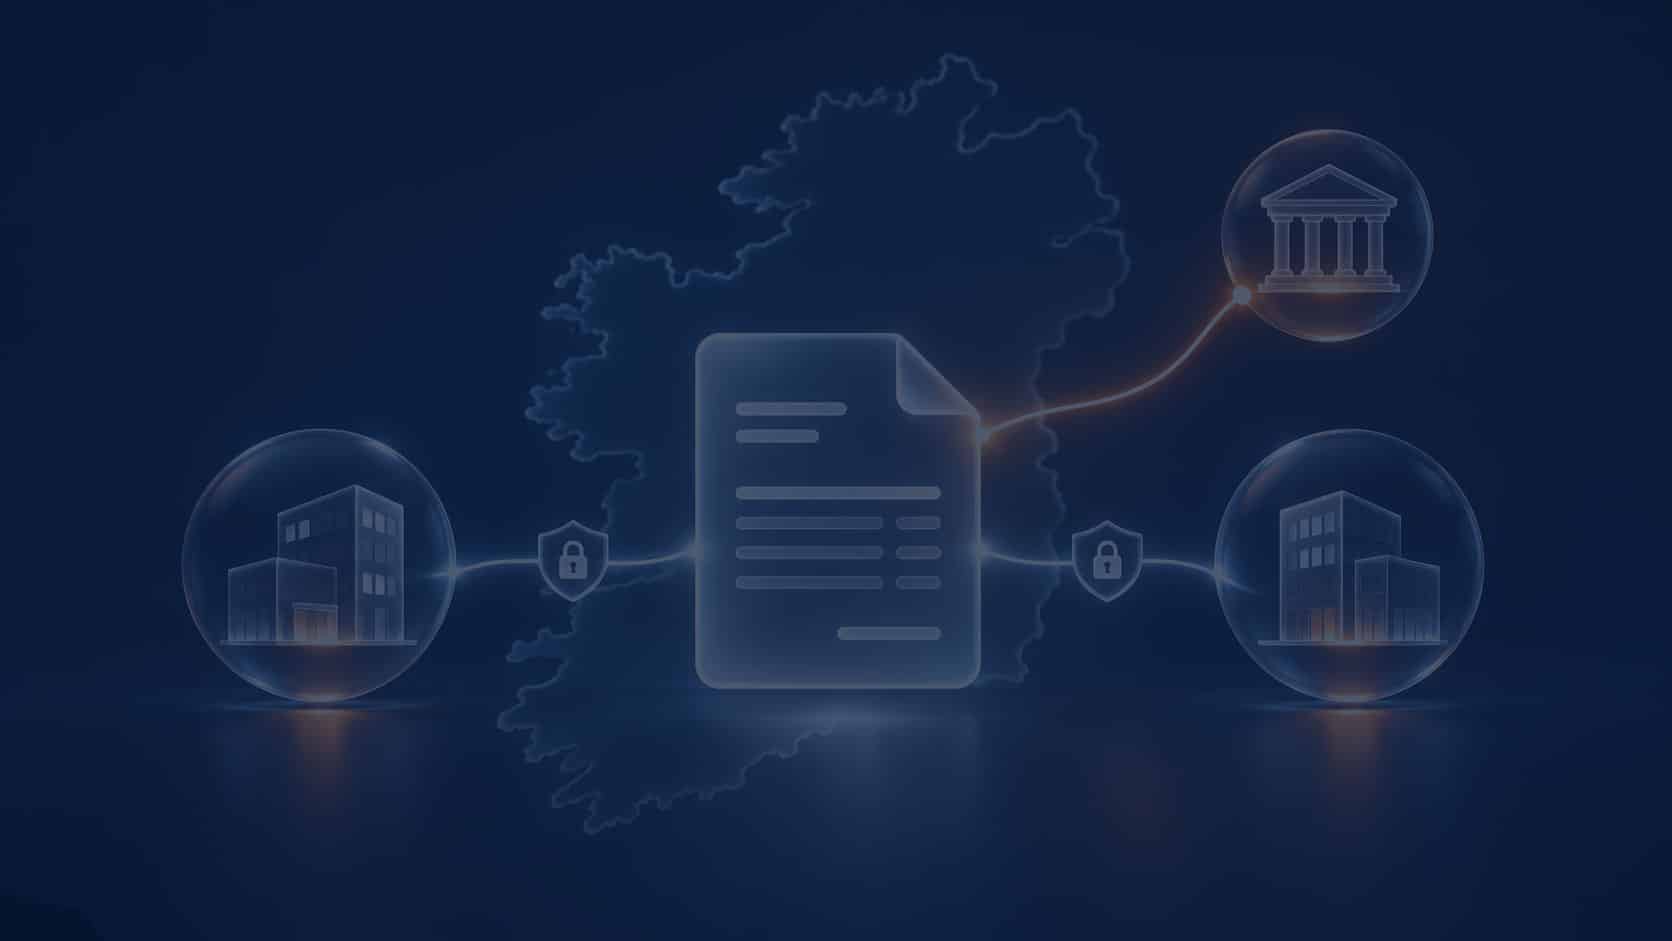
Ireland is not building a central clearance portal that every invoice must pass through before the buyer sees it. Invoices still go from supplier to customer. Peppol is the default network for that exchange, and it is mandated for digital reporting to Revenue.
Today a Peppol invoice has four corners: supplier, supplier’s Access Point, customer’s Access Point, customer.
From Phase One, in-scope invoices add a fifth corner: Revenue.
| Corner | Who | Role |
|---|---|---|
| 1 | Supplier | Issues the structured eInvoice from their own system. |
| 2 | Supplier’s Peppol Access Point | Validates the invoice, sends it to the customer’s Access Point, and reports the specified data to Revenue. |
| 3 | Customer’s Peppol Access Point | Receives the invoice from the network and delivers it. |
| 4 | Customer | Receives the structured eInvoice into their systems. |
| 5 | Revenue | Receives the reporting subset at the time the invoice is issued. |
The invoice still goes from supplier to customer. The fifth corner is the report to Revenue, sent when the invoice is issued.
The supplier reports. The customer does not report on domestic transactions in the announced phases. A software or service provider can transmit the report on the supplier’s behalf.
What stays the same: VAT rates, payment, and how liability is calculated. What is not an eInvoice: PDFs, Word files, scans, and emailed attachments.
Celtrino is already a Peppol Access Point
You do not need to wait until 2028 to get onto Peppol. Celtrino is a certified Peppol Access Point. We can send and receive structured eInvoices (EN 16931 / Peppol BIS Billing) for you now.
You can work in the Celtrino web portal, or we integrate with your ERP. Whichever is easiest.
That covers the exchange path: your invoices reach your trading partners on Peppol, and theirs reach you.
Waiting for Revenue’s five-corner specifications
Real-time reporting is a separate obligation from sending the invoice to your customer. Revenue has confirmed the model (Peppol, five corners, report at the time of issue) but has not yet published the technical specifications: the data fields, validation rules, acknowledgements, and how Access Points connect to Revenue.
Revenue has said it will publish those specifications well ahead of each phase, with test environments in good time before 1 November 2028.
You do not need to track or build against those specifications yourself. That is our job as your Access Point. We are following Revenue’s work closely, and once the specifications are published we will tell you how Celtrino will support the reporting leg and when.
What you can do now
1. Find out where you stand. Are you a Phase One issuer (Revenue will engage directly with the large corporates in scope), or do you only need to receiveeInvoices from 1 November 2028?
2. Get Peppol-ready. Start sending, receiving, or both now. Use the Celtrino web portal, or we integrate with your ERP. Whichever is easiest.
3. Tidy your master data. Make sure customer and supplier records hold correct VAT numbers. They identify both parties on every eInvoice.
4. Leave the technical detail to us. We will keep you updated as Revenue publishes guidance.
Talk to your Celtrino account manager, or email sales@celtrino.com.
This article summarises published programmes in Ireland, the EU, and the UK. It is not tax, legal, or accounting advice. Dates and scope remain subject to legislation and to further official guidance. Europe and UK notes are a snapshot for context; Ireland is the focus of the rest of the article.
Sources: Ireland 2026 update (PDF) · EU ViDA · UK e-invoicing roadmap (28 Oct 2026) · UK digital reporting consultation